[The explosive rise of the prediction markets has energized the debate over the difference between gambling and investing. This is leading to deeper discussions and a better understanding of the human factor behind the perception of risk-taking.
In the wake of the nearly $2 billion spent annually on U.S. sports betting advertising, young people in particular are often criticized for choosing sports betting over investing. But what if we are asking the wrong question? Instead of asking: "Why are younger generations choosing gambling?" perhaps we should be asking: "Why has gambling become better at communicating risk, reward, and probability than investing?"
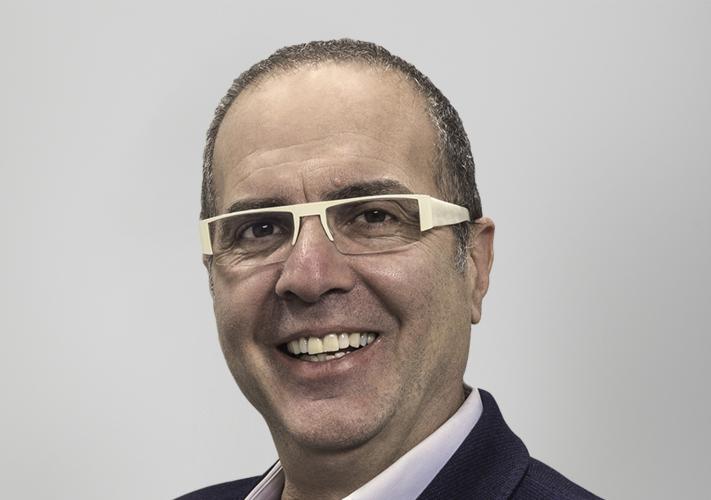
This is the question one of the strongest voices in this debate is asking - Julian Koski, Chief Investment Officer of New Age Alpha, a Rye, New York-based investment management firm.
To continue our exploration of this intriguing and revealing debate - which we started in our previously published interview, “Gambling Vs. Investing and The H-Factor Odds-Based Framework” – I am happy to share Julian’s recent article below, which delves deeper into the uncomfortable question of whether the gambling industry has become better at explaining risk.
The implication is clear - especially in the context of the Great Wealth Transfer of approximately $124 trillion expected to transfer over the next 25 years to younger generations - if advisors and the larger investment industry want to compete for the next generation’s financial attention, it may have to communicate differently.]
Young people aren’t choosing gambling. They’re choosing odds.
By Julian Koski, CIO and Co-Founder, New Age Alpha
Sports betting is competing with investing for young people’s money and attention. The uncomfortable question is whether gambling has become better at explaining risk.
Sports betting has moved rapidly into mainstream American life. In April 2026, the Siena Research Institute and St. Bonaventure University reported that 27% of US adults had an active online sportsbook account, up from 22% in 2025 and 19% in 2024. Among men ages 18 to 49, 52% had an active account.¹
The easiest explanation is that young people have become more reckless. They want stimulation, rapid rewards, and the possibility of getting rich quickly. There’s almost certainly some truth in that, but it misses what the betting industry has done so effectively.
It has made uncertainty understandable.
When someone places a sports bet, the proposition is clear. There’s a stake, an outcome, and a potential payout. The odds may be unfavorable, and they incorporate an economic advantage for the sports book, but the customer can see the wager being offered.
There’s no pretense that the future is known. There are only odds.
That clarity appears to be part of the attraction. Among bettors surveyed by Siena Research Institute in 2026, 92% described online sports betting as fun and exciting, 89% said it made watching live games more interesting, 85% said they enjoyed researching players and teams, and 85% said they participated because they thought they could make money. Another 83% enjoyed making small bets that could produce much larger payouts.
Those findings complicate the idea that betting is simply mindless risk-taking. Bettors are often studying statistics, forming opinions, and attempting to translate information into an assessment of probability. They may be overestimating their skill or misunderstanding the bookmaker’s advantage, but they’re participating in a system that gives them an intelligible relationship between risk and reward.
Investing rarely feels that straightforward.
A new investor is introduced to valuations, earnings estimates, analyst targets, volatility, diversification, risk tolerance, market cycles, and competing economic forecasts. Each concept may be useful, but together they can leave the investor with plenty of information and no clear answer to the question that matters most:
What are my chances?
The investment industry usually responds with an outlook. The gambling industry responds with odds.
That doesn’t make gambling the better financial proposition. Quite the opposite. The US Securities and Exchange Commission describes investing as placing money into assets such as stocks or bonds with the expectation of earning a return over time, while recognizing that all investments involve risk and market fluctuations. It also emphasizes that regularly investing over a long period allows investors to benefit from compound growth, in which returns can be earned on both the original investment and previous returns.2
Time, in other words, is one of the young investor’s greatest advantages. Unfortunately, it’s also one of investing’s least exciting features.
Gambling compresses the experience. A bettor can form a view in the morning, place a wager in the afternoon and know the outcome that evening. Investing asks someone to contribute money today in exchange for a financial benefit that may not become meaningful for years or even decades. One provides a rapid emotional payoff. The other offers something potentially more valuable, but much harder to feel.
The age-based investment data show why this early contest for attention matters. According to the Investment Company Institute, 33% of Gen Z households owned mutual funds in 2025, compared with 50% of Millennial households, 57% of Gen X households, 59% of Baby Boomer households and 63% of Silent Generation households. The figures include mutual funds held through employer-sponsored retirement plans and personal accounts, so they provide a broader picture than brokerage ownership alone. 3
These differences shouldn’t be interpreted as proof that older generations are naturally more prudent. Older households have had more time to participate in retirement plans and accumulate assets. The Investment Company Institute notes that Baby Boomer households’ large share of mutual fund assets reflects the time they’ve had to build savings through employer-sponsored plans, individual retirement accounts, and other personal accounts.
The FINRA Investor Education Foundation provides another perspective. Its 2024 research found that 21% of US adults under 35 owned investments outside retirement accounts, down from 26% in 2021. Because this measure excludes workplace retirement accounts, it shouldn’t be mistaken for the total proportion of younger adults who invest. It does, however, show that non-retirement investment ownership among this group remains limited.4
There’s therefore no basis for saying that an entire generation has abandoned investing for gambling. The evidence supports a subtler argument. Younger people are participating in investing, but they’re also encountering a betting industry that’s exceptionally good at transforming uncertainty into a simple, immediate, and engaging experience.
The smartphone has made that experience almost frictionless. A peer-reviewed study published in the International Journal of Mental Health and Addiction interviewed 33 Australian sports bettors ages 18 to 29 5. Participants’ accounts indicated that the combination of smartphones, online gambling and betting apps provided instantaneous access to wagering and facilitated more frequent, spontaneous, and varied betting, including riskier bets and attempts to chase losses. Because this was a small qualitative study, it can’t tell us how widespread those behaviors are, but it helps explain how the design of mobile betting can influence the experience of young adults who already wager regularly.
The potential harm is visible in the larger US survey data. A total of 60% of bettors in the 2026 Siena Research Institute study said they had increased a bet in an attempt to recover a previous loss, while 31% said someone had expressed concern about their use of online sportsbooks.
This is the contradiction at the center of the betting experience. The individual wager appears transparent, but the long-term economics are considerably less attractive. The bettor can see the quoted odds without necessarily understanding what repeated participation at those odds is likely to do to their capital.
Investing has almost the opposite problem. Its long-term economic proposition can be powerful, but the immediate experience is abstract, complicated, and frequently obscured by the industry’s own language.
This helps explain why lecturing young people about gambling is unlikely to be enough. The investment industry also needs to examine its own failure to communicate. It presents people with forecasts, narratives, and measures of historical volatility, but seldom translates those ingredients into a comprehensible decision about the odds of losing capital.
Worse, investing is frequently marketed through stories that make an uncertain future appear more predictable than it is. Investors hear why a company will dominate its market, why a trend is unstoppable, or why an experienced manager is positioned to outperform. The story creates confidence, but confidence isn’t probability.
Sports betting, for all its dangers, begins with an acknowledgment that the outcome is uncertain.
Investing should do the same.
The lesson isn’t that investment platforms should imitate casinos, accelerate trading, or turn wealth creation into entertainment. Nor is it that published betting odds make gambling fair. The lesson is that people respond to clear relationships between risk, reward, and uncertainty.
Young people are already willing to study statistics, compare possible outcomes, and make decisions without knowing what’ll happen next. They aren’t necessarily rejecting probabilistic thinking.
They may be searching for it.
The gambling industry puts the odds on the screen. The investment industry gives them an outlook, a story, and a chart of what happened before they arrived.
If investing wants to compete for the next generation’s financial attention, it’ll have to communicate differently.
It’s no longer good enough to have a great-performing product. That might have been good enough for the Baby Boomer generation. These younger generations are in search of something more. Something different. Something that excites them.
A good place to start is by answering a more honest question.
Not, what do we think will happen? But: what are the odds?
References:
1. Siena Research Institute & St. Bonaventure University. New York State Online Sports Betting Research Study, 2026.
2. U.S. Securities and Exchange Commission, Investor.gov. Investing Basics.
3. Investment Company Institute. Ownership of Mutual Funds, Shareholder Sentiment and Use of the Internet, 2025.
4. FINRA Investor Education Foundation. National Financial Capability Study, 2024.
5. Russell AMT, Hing N, Li E, Vitartas P. Young Adult Sports Betting: The Impact of Sports Betting Websites and Online Technology on Problem Gambling. International Journal of Mental Health and Addiction.
The Institute for Innovation Development is an educational and business development catalyst for growth-oriented financial advisors and financial services firms determined to lead their businesses in an operating environment of accelerating business and cultural change. We operate as a business innovation platform and educational resource with FinTech and Financial Services firm members to openly share their unique perspectives and activities.
This interview is for informational purposes only. The goal is to build awareness and stimulate open thought leadership discussions on new or evolving industry approaches and thinking to facilitate next-generation growth, differentiation, and unique client/community engagement strategies. The Institute was launched with the support and foresight of our founding sponsors — Ultimus Fund Solutions, FLX Networks, ETF Global, The Wealth Mosaic, SME Forum, Advisorpedia, Pershing, Fidelity, and Charter Financial Publishing (publisher of Financial Advisor and Private Wealth magazines).